If you’re planning to buy a home in Australia, one of the first questions you may have is: how much would I need to repay on a $500,000 mortgage?
Your actual repayment depends on several factors, including your interest rate, loan term and repayment frequency.
For example, a $500,000 home loan over 30 years can have significantly different repayments depending on whether the interest rate is 5%, 6% or 7%.
In this guide, we’ll look at example repayments and explain how mortgage repayments are calculated.
Want to calculate your own repayment? Try our Mortgage Calculator Australia to estimate your monthly, fortnightly and weekly repayments.
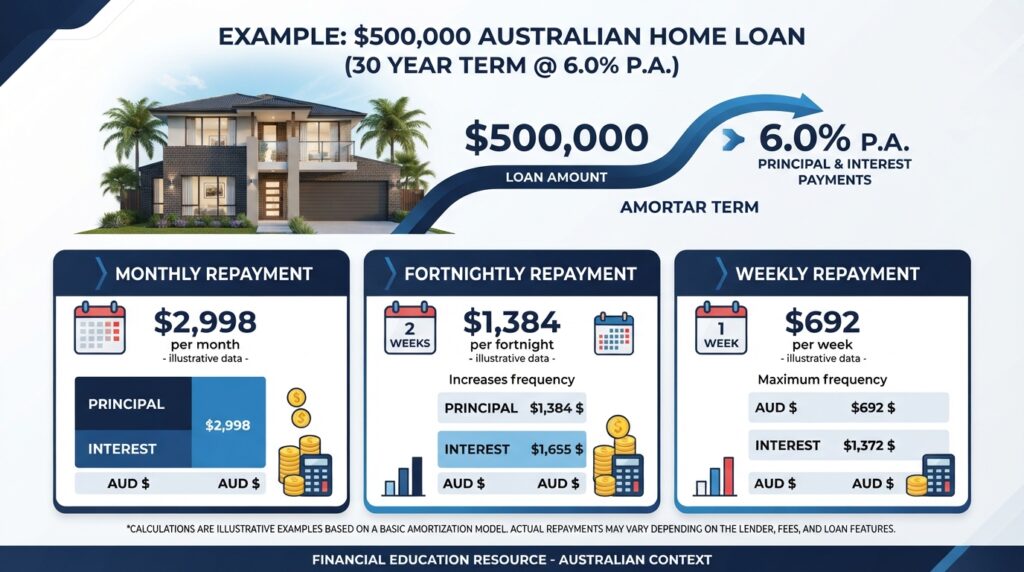
Table of Contents
- What Is the Repayment on a $500,000 Mortgage?
- How Much Is a $500,000 Mortgage at 6%?
- What About a 25-Year Mortgage?
- What Affects Your Mortgage Repayment?
- How Do You Calculate a Mortgage Repayment?
- Can a $500,000 Mortgage Be Affordable?
- How Can You Reduce Mortgage Interest?
- Frequently Asked Questions
What Is the Repayment on a $500,000 Mortgage?
A $500,000 principal-and-interest home loan will have different repayments depending on the interest rate and loan term.
For example, assuming a 30-year loan term:
| Interest Rate | Approx. Monthly Repayment |
|---|---|
| 5% | $2,684 |
| 6% | $2,998 |
| 7% | $3,327 |
| 8% | $3,669 |
These are illustrative calculations. Your actual repayment may differ depending on your lender, loan structure, fees and other conditions.
How Much Is a $500,000 Mortgage at 6%?
Suppose you borrow $500,000 at 6% interest over 30 years.
Your estimated principal-and-interest repayment would be approximately:
Monthly: $2,998
Fortnightly equivalent: about $1,384
Weekly equivalent: about $692
Over the full 30-year term, the total amount paid would be substantially higher than the original $500,000 because of interest.
This is why comparing interest rates and understanding your loan term is important when planning a home purchase.
What About a 25-Year Mortgage?
A shorter loan term generally means higher regular repayments, but the loan may be paid off sooner.
For example, at an illustrative 6% interest rate:
| Loan Term | Approx. Monthly Repayment |
|---|---|
| 20 years | $3,582 |
| 25 years | $3,222 |
| 30 years | $2,998 |
The exact figures depend on the loan structure and lender.
A longer term can reduce the regular repayment, but keeping a loan for longer can mean paying more interest overall.
What Affects Your Mortgage Repayment?
Several factors can affect the amount you need to repay.
1. Interest Rate
The interest rate is one of the biggest factors.
A higher interest rate generally means a higher repayment and more interest paid over the life of the loan.
Even a relatively small difference in the interest rate can make a noticeable difference over many years.
2. Loan Term
The loan term is the amount of time you have to repay the mortgage.
A 30-year loan generally has lower regular repayments than a 20-year loan, assuming the same loan amount and interest rate.
However, a longer term can result in more interest being paid over time.
3. Deposit
Your deposit affects how much you need to borrow.
For example:
Property price: $625,000
Deposit: $125,000
Loan: $500,000
Your deposit would represent 20% of the property price.
You can use our Home Loan Deposit Calculator Australia to estimate the deposit and loan amount for a property.
4. Loan Type
Home loans can have different structures, such as principal-and-interest or interest-only arrangements.
The repayment calculation can therefore differ depending on the loan structure.
5. Fees and Other Costs
Your overall home-buying costs may include more than the loan repayment itself.
Depending on your circumstances, you may also need to consider costs such as government charges, lender fees, insurance and other property-related expenses.
How Do You Calculate a Mortgage Repayment?
A standard principal-and-interest mortgage uses the loan amount, interest rate and number of repayments to calculate the regular repayment.
The calculation takes both:
- Principal — the amount you borrowed
- Interest — the cost of borrowing the money
into account.
As you make repayments, part of the payment goes toward interest and part goes toward reducing the loan balance.
You don’t need to calculate this manually.
You can use our Mortgage Calculator Australia to enter your own loan amount, interest rate and loan term.
Can a $500,000 Mortgage Be Affordable?
Whether a $500,000 mortgage is affordable depends on your individual financial circumstances.
Lenders may consider factors such as:
- Income
- Existing debts
- Living expenses
- Loan amount
- Interest rate
- Loan term
- Deposit
- Employment and financial circumstances
A calculator can give you an estimate, but it doesn’t guarantee that a lender will approve a particular loan.
If you’re trying to estimate your potential borrowing capacity, you can also use our Borrowing Power Calculator Australia.
Useful Australian Resources
For general information about home loans and mortgage costs, you can visit MoneySmart, the Australian Government’s financial guidance website.
MoneySmart:
MoneySmart – Mortgage Calculator
For information about Australian home loan and lending requirements, you can also refer to APRA, the Australian Prudential Regulation Authority.
How Can You Reduce Mortgage Interest?
There are several strategies borrowers may consider when managing a home loan.
Make additional repayments
If your loan allows additional repayments, paying more than the required amount can reduce the outstanding balance faster.
Consider an offset account
An offset account can reduce the balance used to calculate interest on an eligible home loan.
You can learn more with our Mortgage Offset Calculator Australia.
Compare loan options
Interest rates, fees and loan features can vary between lenders and products.
It’s important to compare the terms and conditions rather than looking at the interest rate alone.
Frequently Asked Questions
How much is a $500,000 mortgage per month in Australia?
It depends on the interest rate and loan term. For example, a $500,000 loan at an illustrative 6% rate over 30 years has a principal-and-interest repayment of approximately $2,998 per month.
How much is a $500,000 mortgage per fortnight?
Using the same illustrative 6% rate and 30-year term, the monthly repayment is approximately $2,998. An annualised fortnightly equivalent is around $1,384.
Actual lender fortnightly repayments can differ depending on how the lender calculates them.
How much deposit do I need for a $500,000 mortgage?
There isn’t one universal deposit amount. It depends on the property price, loan amount, lender requirements and your circumstances.
For example, if you purchased a $625,000 property and borrowed $500,000, the deposit would be $125,000, or 20%.
Is a 30-year mortgage better than a 20-year mortgage?
The two loan terms have different repayment and interest implications. A 30-year term generally has lower regular repayments, while a 20-year term generally requires higher regular repayments but can reduce the time over which interest is charged.
The appropriate choice depends on your circumstances.
Does a higher interest rate increase mortgage repayments?
Generally, yes. For the same loan amount and term, a higher interest rate generally results in a higher principal-and-interest repayment.
Related Australian Calculators
You may also find these calculators useful:
- Mortgage Calculator Australia
- Borrowing Power Calculator Australia
- Home Loan Deposit Calculator Australia
- LMI Calculator Australia
- Stamp Duty Calculator Australia
- Home Affordability Calculator Australia
- Mortgage Offset Calculator Australia
⚠️ Important Note
The repayment examples in this article are illustrative estimates, not personalised financial advice. Actual repayments can vary depending on the lender, interest rate, loan structure, fees and individual circumstances.